
What Happens If Your Spouse Hides Cryptocurrency During an Illinois Divorce?
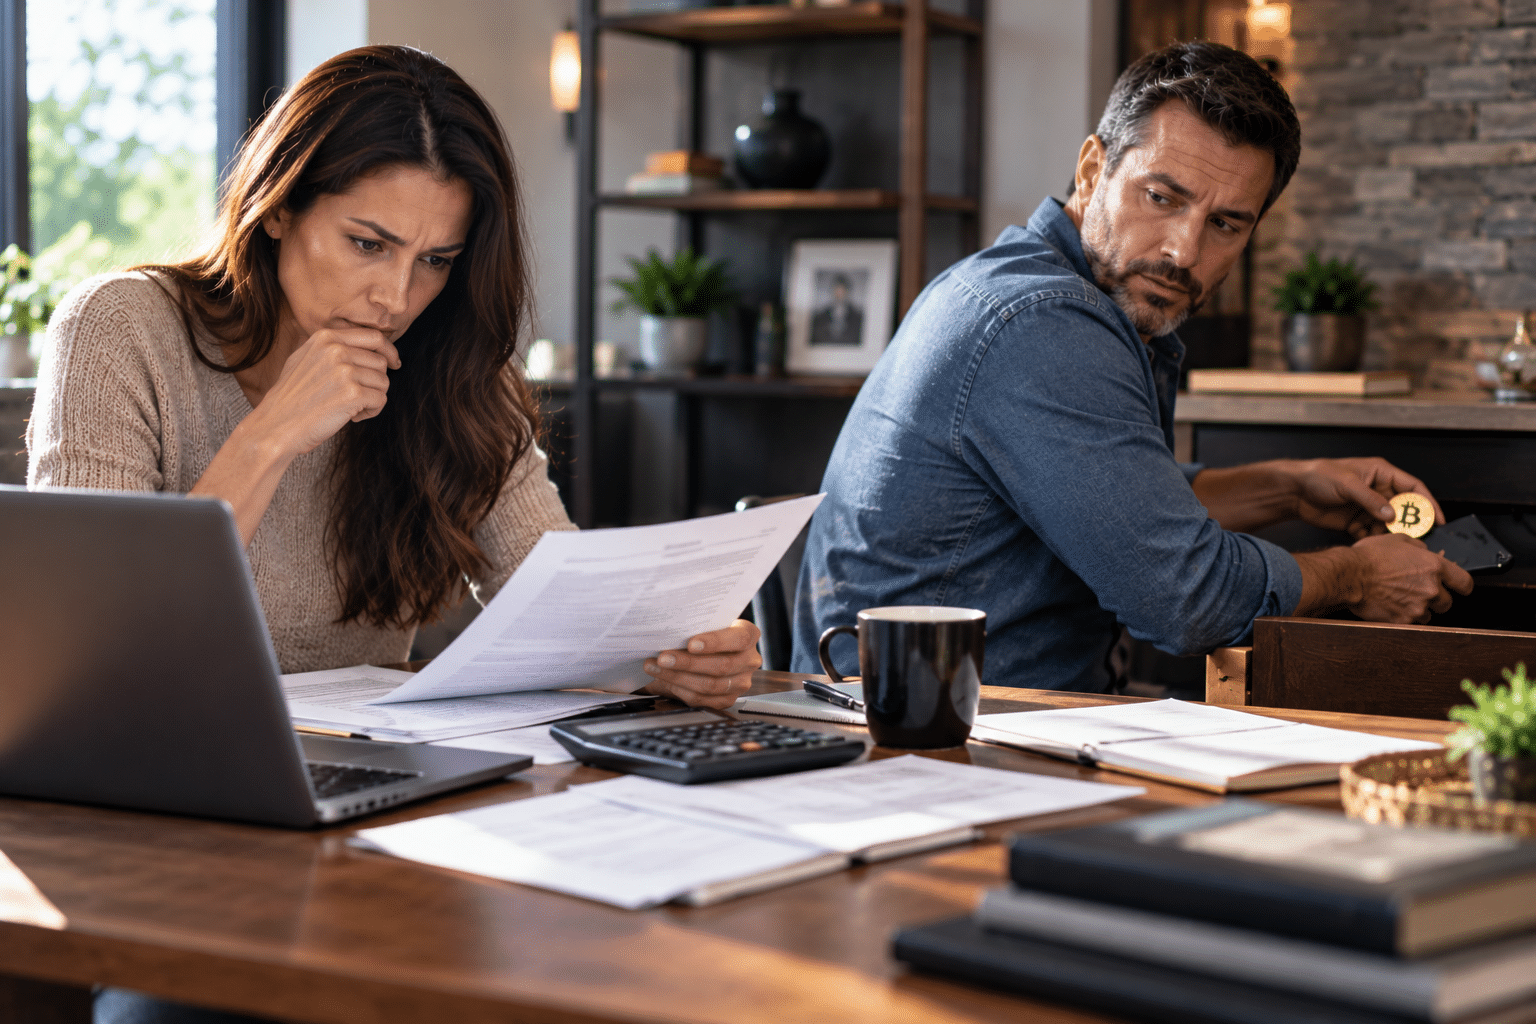
Cryptocurrency can create serious problems in an Illinois divorce when one spouse owns Bitcoin, Ethereum, stablecoins, or other digital assets that the other spouse does not know about. Unlike a traditional bank account, cryptocurrency can sometimes be transferred between digital wallets without a familiar monthly statement arriving in the mail. That does not mean cryptocurrency is beyond the reach of an Illinois divorce court.
If digital assets were acquired during the marriage, they may be marital property even when only one spouse knows the wallet address, controls the private keys, or maintains the cryptocurrency exchange account. When I represent someone in a divorce involving suspected hidden cryptocurrency, I focus on determining what assets exist, when they were acquired, where they were transferred, what they are worth, and whether marital funds were improperly concealed or spent.
Cryptocurrency Can Be Marital Property In Illinois
Illinois law generally treats property acquired by either spouse after the marriage and before the divorce judgment as marital property unless a statutory exception applies. Under 750 ILCS 5/503(a) and (b), property acquired during the marriage is generally presumed to be marital property. That principle is broad enough to include cryptocurrency, even though the statute does not specifically use the words Bitcoin or cryptocurrency.
For example, if a spouse purchased $40,000 of Bitcoin during the marriage using employment income, the fact that the cryptocurrency account is solely in that spouse’s name does not ordinarily make the Bitcoin that spouse’s separate property. Title and control are not the only considerations. I look at when the cryptocurrency was acquired and the source of the money used to acquire it.
There are situations in which cryptocurrency may be non-marital property. A spouse might have purchased Bitcoin before the marriage, received digital assets as a genuine gift or inheritance, or acquired cryptocurrency using qualifying non-marital property. Section 503 contains specific categories of non-marital property, and the spouse claiming that property falls within one of those exceptions may need evidence supporting that classification.
Hiding Cryptocurrency Does Not Remove It From The Marital Estate
Moving cryptocurrency into another wallet does not necessarily change who owns it for divorce purposes. Neither does transferring digital assets from an exchange account into a private hardware wallet.
A spouse might attempt to conceal cryptocurrency by transferring coins among several wallets, opening exchange accounts that the other spouse does not know about, converting one digital asset into another, moving assets to an exchange outside the United States, or transferring cryptocurrency to a friend or relative. Other spouses may claim that cryptocurrency was lost, sold, or spent when the blockchain or financial records tell a different story.
Illinois courts divide marital property in “just proportions” after considering the statutory factors listed in 750 ILCS 5/503(d). The court is not required to accept a spouse’s unsupported statement that a digital asset disappeared. Financial records, exchange information, electronic records, tax documents, bank transactions, and blockchain activity may provide evidence concerning what happened to the asset.
Divorce Discovery Can Expose Digital Assets
One of the most important parts of a cryptocurrency divorce case may be financial discovery. Illinois Supreme Court Rule 201 generally permits discovery concerning matters relevant to the litigation, while Rule 214 provides procedures for requesting documents and electronically stored information.
Cryptocurrency investigations may involve requests for exchange statements, transaction histories, wallet addresses, tax records, bank statements, screenshots, account records, emails, electronic files, and records showing purchases made through exchanges. Deposits from a marital checking account to a cryptocurrency exchange can also provide a starting point even when the current cryptocurrency account is not immediately known.
A person’s tax documents can be particularly useful. Cryptocurrency transactions can create tax reporting obligations, and records from accountants, tax preparation software, exchanges, or financial institutions may identify activity that does not appear elsewhere in the household’s ordinary financial records.
I may also compare income, bank withdrawals, credit card transactions, transfers, and known cryptocurrency purchases. One isolated transfer might not establish concealment, but a consistent financial trail may help identify assets that should be investigated.
Blockchain Transactions Can Leave A Financial Trail
Cryptocurrency can provide privacy, but many digital currencies do not provide complete anonymity. Public blockchains can preserve transaction information that may remain accessible long after a transfer occurs.
If a known wallet address can be connected to a spouse, transaction history may reveal transfers to additional addresses. Records from cryptocurrency exchanges can sometimes help connect a real person’s identity with particular transactions or wallet addresses. Depending on the amount at issue and complexity of the case, forensic accounting or digital-asset analysis may be appropriate.
Tracing can become more difficult when cryptocurrency has passed through numerous wallets, decentralized exchanges, foreign exchanges, privacy-focused services, or other digital-asset platforms. Difficulty tracing an asset, however, is different from proving that the asset no longer exists.
Hidden Cryptocurrency May Support A Dissipation Claim
Illinois law specifically requires courts dividing marital property to consider dissipation of marital property. 750 ILCS 5/503(d)(2) establishes procedural requirements for a dissipation claim, including notice requirements and time limitations.
The statute generally requires notice of an intent to claim dissipation no later than 60 days before trial or 30 days after discovery closes, whichever is later. The notice must identify the relevant period of marital breakdown, the property allegedly dissipated, and when the alleged dissipation occurred. The statute also limits how far back a dissipation claim may reach.
A cryptocurrency transfer is not automatically dissipation. The circumstances matter. Buying cryptocurrency as an ordinary marital investment can be very different from secretly transferring marital cryptocurrency to another person during the breakdown of the marriage or using marital digital assets for purposes unrelated to the marriage.
If I believe dissipation may have occurred, timing is important because Section 503 establishes specific requirements for asserting the claim.
Cryptocurrency Valuation Can Become A Major Issue
Finding cryptocurrency is only part of the problem. The asset also must be valued.
Cryptocurrency prices can rise or fall substantially during a divorce case. A digital asset worth $100,000 when the divorce petition is filed might be worth considerably more or less by the time the property issues are resolved. Courts must make factual findings concerning the classification and value of property when making a property award under Section 503.
Transaction dates also matter. If cryptocurrency was purchased before marriage, additional coins were purchased during marriage, and the account experienced numerous trades afterward, determining the marital and non-marital components can require careful tracing.
I also consider transaction fees, tax consequences, basis information, and the practical method used to divide an account. A proposed settlement that simply assigns one spouse a certain dollar value of cryptocurrency may fail to account for tax basis or market changes.
Failure To Cooperate With Discovery Can Carry Consequences
A spouse should not assume that refusing to provide exchange records or electronic financial information will make the issue disappear. Illinois Supreme Court Rule 219 authorizes courts to impose consequences when a party unreasonably fails to comply with discovery requirements or court orders.
The appropriate response depends on what happened, what information was withheld, whether a court order was violated, and the effect on the case. Discovery disputes may also increase attorney’s fees and litigation costs. 750 ILCS 5/508 provides authority for attorney-fee awards in proceedings under the Illinois Marriage and Dissolution of Marriage Act under the circumstances described in that section.
If cryptocurrency concealment is suspected, preserving electronic and financial evidence early can be important. Waiting until shortly before trial may make tracing transactions more difficult and can create problems with deadlines applicable to property and dissipation claims.
Cryptocurrency Concealment And Parenting Time Are Separate Issues
Property division and parenting time involve different legal standards. Under 750 ILCS 5/602.7, Illinois courts allocate parenting time according to the child’s best interests. The statute specifically states that a court should not consider parental conduct that does not affect the parent’s relationship with the child.
For that reason, hiding cryptocurrency does not automatically mean a parent should receive less parenting time. Financial conduct could become relevant to other issues in a family law proceeding depending on the circumstances, but parenting decisions remain focused on the child’s best interests and the statutory parenting factors.
I handle family law cases involving both sides of divorce proceedings as well as property division, child custody and allocation of parental responsibilities, parenting time and visitation rights, paternity, support, and related disputes. When several of these issues arise in the same case, each must be evaluated under the legal standards that apply to that particular issue.
Frequently Asked Questions About Hidden Cryptocurrency In An Illinois Divorce
How Can I Find Out If My Spouse Owns Cryptocurrency?
I usually begin with the financial records that are already available. Bank statements may show payments to cryptocurrency exchanges, transfers through payment platforms, wire transfers, or unexplained withdrawals. Tax returns and related records can also contain information connected with digital-asset transactions.
Discovery can then be used to request records concerning cryptocurrency accounts, wallets, transactions, and electronically stored information. The investigation may expand if the records reveal additional exchanges, wallet addresses, or transfers. In cases involving significant digital assets, financial or blockchain analysis may also be considered.
The fact that you do not know a spouse’s wallet password does not necessarily mean there is no way to investigate the cryptocurrency.
Is Cryptocurrency Marital Property If The Account Is Only In My Spouse’s Name?
It can be. Under 750 ILCS 5/503, property acquired after marriage and before the divorce judgment is generally presumed to be marital property unless a statutory exception applies. The name appearing on an account is therefore not the end of the analysis.
If your spouse purchased cryptocurrency during the marriage with marital income, those digital assets may be part of the marital estate even if you never had access to the account. If your spouse claims the cryptocurrency is non-marital, the acquisition history, source of funds, and applicable statutory exception should be examined carefully.
What If My Spouse Bought Cryptocurrency Before We Were Married?
Cryptocurrency acquired before marriage may qualify as non-marital property under 750 ILCS 5/503(a). The analysis can become more complicated when additional cryptocurrency was acquired during the marriage or marital money was mixed with non-marital funds.
Detailed transaction records can become important when an account contains both pre-marital and marital activity. I may examine purchase dates, wallet transfers, exchange records, bank deposits, and transaction history to determine whether the asset can be traced and properly classified.
Simply stating that an account existed before marriage does not necessarily establish that every asset currently held in that account is non-marital.
What Happens If My Spouse Transfers Cryptocurrency To A Friend Before The Divorce?
The transfer should be investigated. A transfer does not necessarily prevent an Illinois divorce court from considering what happened to marital property.
The circumstances are critical. I would want to know when the transfer occurred, how much cryptocurrency was transferred, whether anything was received in exchange, who received it, whether the transaction occurred after the marriage began breaking down, and whether the transfer benefited the marriage.
Depending on the evidence, the transaction may raise property-division or dissipation issues under 750 ILCS 5/503(d). Because Illinois law establishes deadlines and notice requirements for dissipation claims, these transactions should be examined promptly.
Speak With A Schaumburg Family Law Lawyer About Hidden Cryptocurrency
Cryptocurrency can complicate an Illinois divorce because determining ownership may require more than reviewing ordinary bank and investment statements. If you believe your spouse owns undisclosed Bitcoin, Ethereum, stablecoins, or other digital assets, I can examine the financial history, available records, property classification, discovery options, valuation issues, and possible dissipation concerns. I can also represent a spouse who has been accused of hiding cryptocurrency and needs to establish the source, ownership, transaction history, or non-marital character of digital assets.
At the Law Office of Fedor Kozlov, I handle either side of divorce proceedings and represent clients in matters involving marital-property division, allocation of parental responsibilities, child custody decisions, parenting time and visitation rights, paternity, support, and other Illinois family law issues. When cryptocurrency is involved, addressing the digital assets early can help ensure that the financial issues are based on documented facts rather than speculation.
If hidden cryptocurrency is affecting your divorce, or you are concerned that Bitcoin or other digital assets have not been properly disclosed, contact the Law Office of Fedor Kozlov to discuss your circumstances. I represent clients in Schaumburg, throughout Chicago, and across Illinois in divorce and family law matters involving complex financial and parenting issues. Contact our Schaumburg divorce attorney at the Law Office of Fedor Kozlov by calling (847) 241-1299 to receive a consultation.
